S corp filingThe page has to leave.
The second proof is each K-1 in the shareholder's hands, not only in a portal.
Count the copies.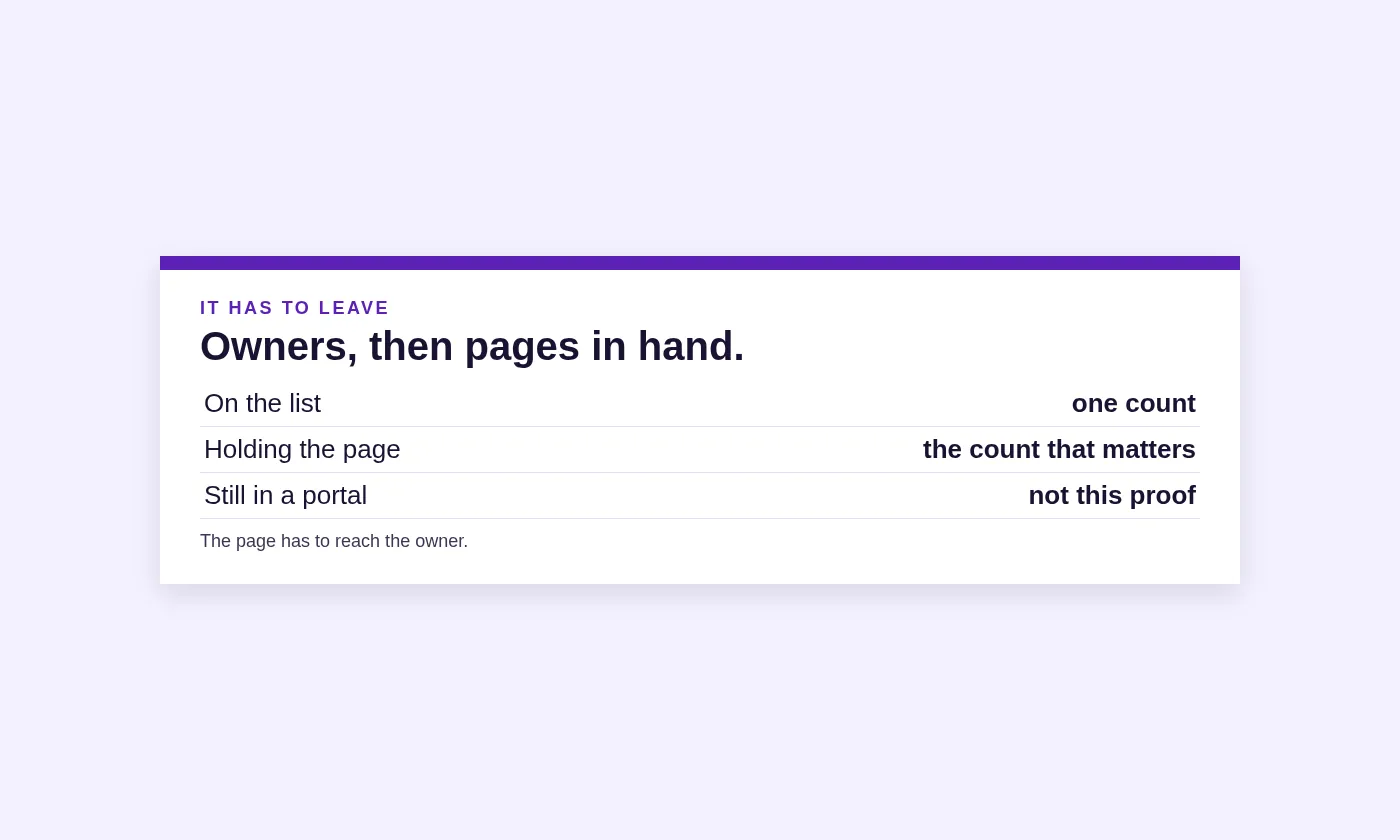
The second proof is each K-1 in the shareholder's hands, not only in a portal.
Count the copies.We start with the owner list. Every person who should receive a Schedule K-1 is a name on that list. Then we ask a plainer question. Who is holding the page. A login does not answer it. A portal can show the page to anyone with the password and still leave every owner without a copy they can keep.
The send count has to match the owner count. If two people own the company and one PDF was downloaded by the person who runs the books, the count is one, or it is zero, depending on whether that person is also an owner. We do not round up.
The company filing date exists so the K-1 can arrive before the personal return is due. That is the reason we care about the company date. We do not teach the personal extension on this page. We do not tell you how to move your own individual due date. We keep the company work early enough that the page can leave.
A K-1 that is still a draft inside software is not a copy in someone's hands. The draft can change when a closed month is reopened because a receipt was found. We would rather hold the page until the months are closed than send a page we expect to replace.
The K-1 reports the owner's share of the company's results. It also has to be believable next to the equity lines. Contribution, draw, and profit that remained are separate lines, and merging them is how the page stops matching the books. If those lines were merged, the second proof is not really full.
A loss still has a ceiling. The ceiling is the owner's basis. When someone wants that ceiling written down, Form 7203 is the sheet they open, and we leave the sheet off this page. The loss waits when the ceiling is too low, and we say that before anyone treats the K-1 as cash they can use.
Tell us the owner count and how many pages actually went out. If the number is short, we leave the proof empty and we say so.
Owner count, and how many people are holding a K-1.

You will be talking to the Steven Palmieri practice.